Roof insurance claims in Fayetteville, documented so they go through
Photos, measurements and a storm report before you call your carrier; a walk-through with your adjuster on the roof; a build to the approved scope. Your deductible stays yours — always.
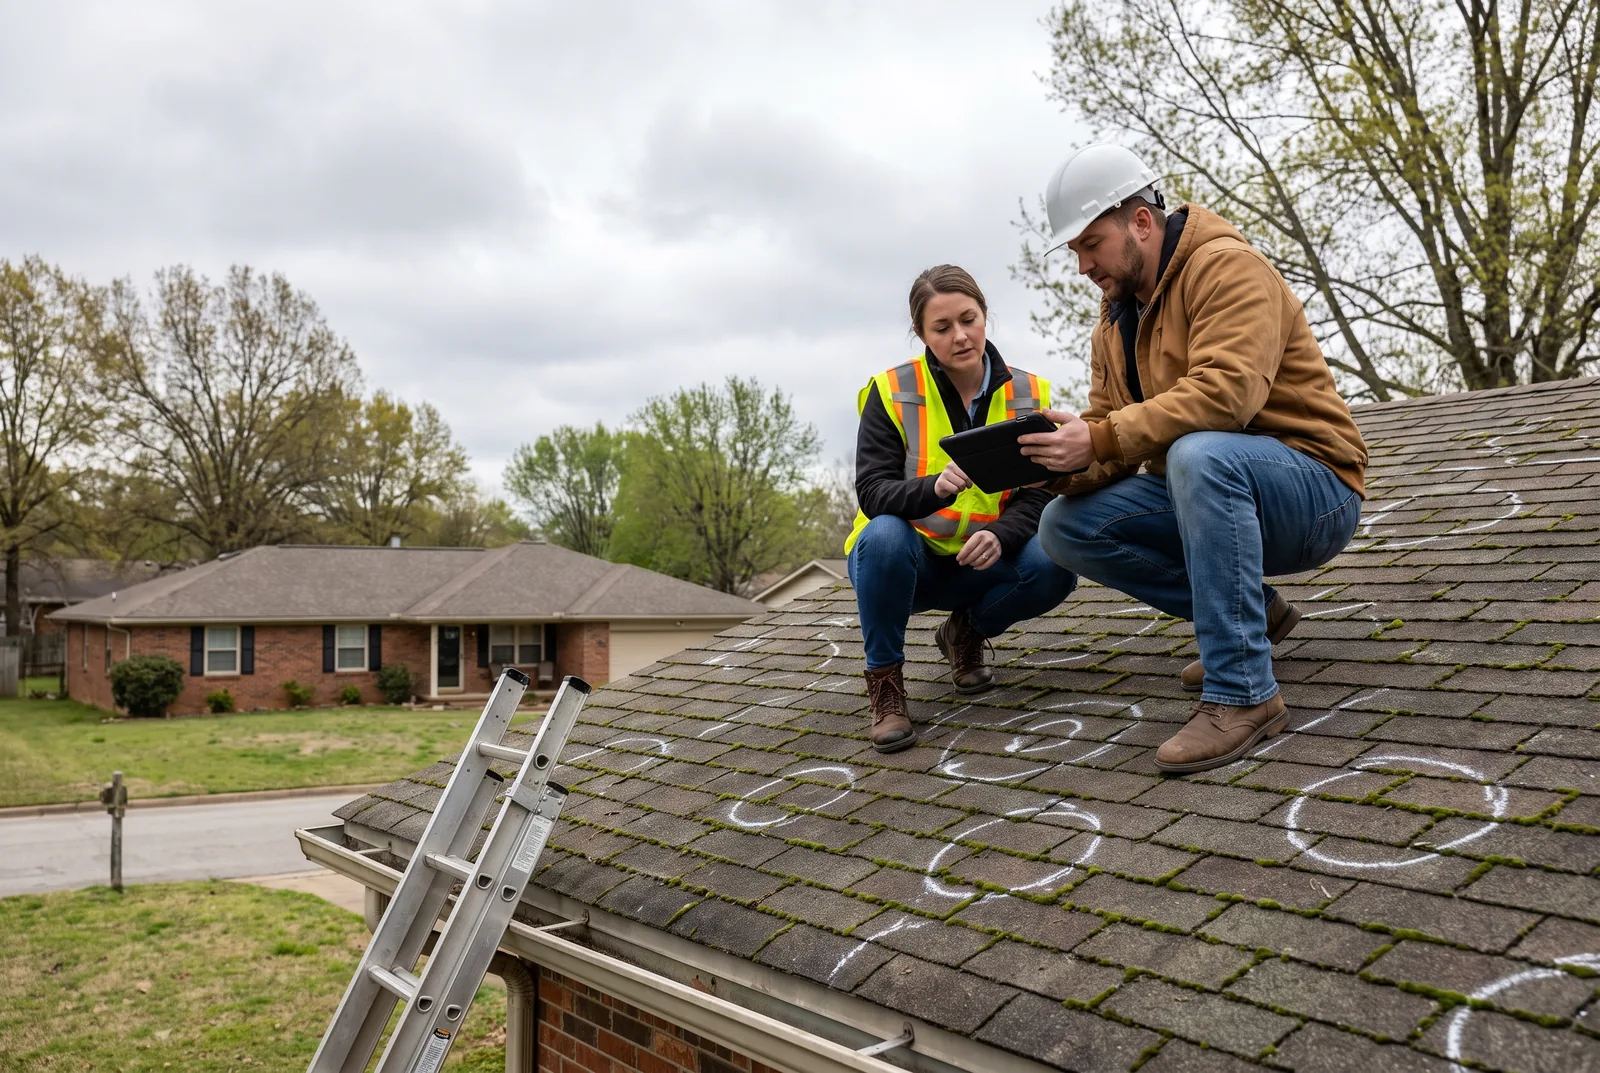
An Arkansas roof claim in 2026 is not the same as one in 2019. After loss ratios hit 171 percent in 2023 and three in-state home insurers shut down, carriers rewrote roof coverage across the state: many policies now pay full replacement cost on a roof for only about seven years and then depreciate it on a schedule, roofs past twenty years may be covered for actual cash value only, and separate wind/hail deductibles — often a percentage of the home's value rather than a flat $1,000 — are now common. What that means for you is that the documentation has to be right the first time, and you need to know what your policy will actually pay before you file.
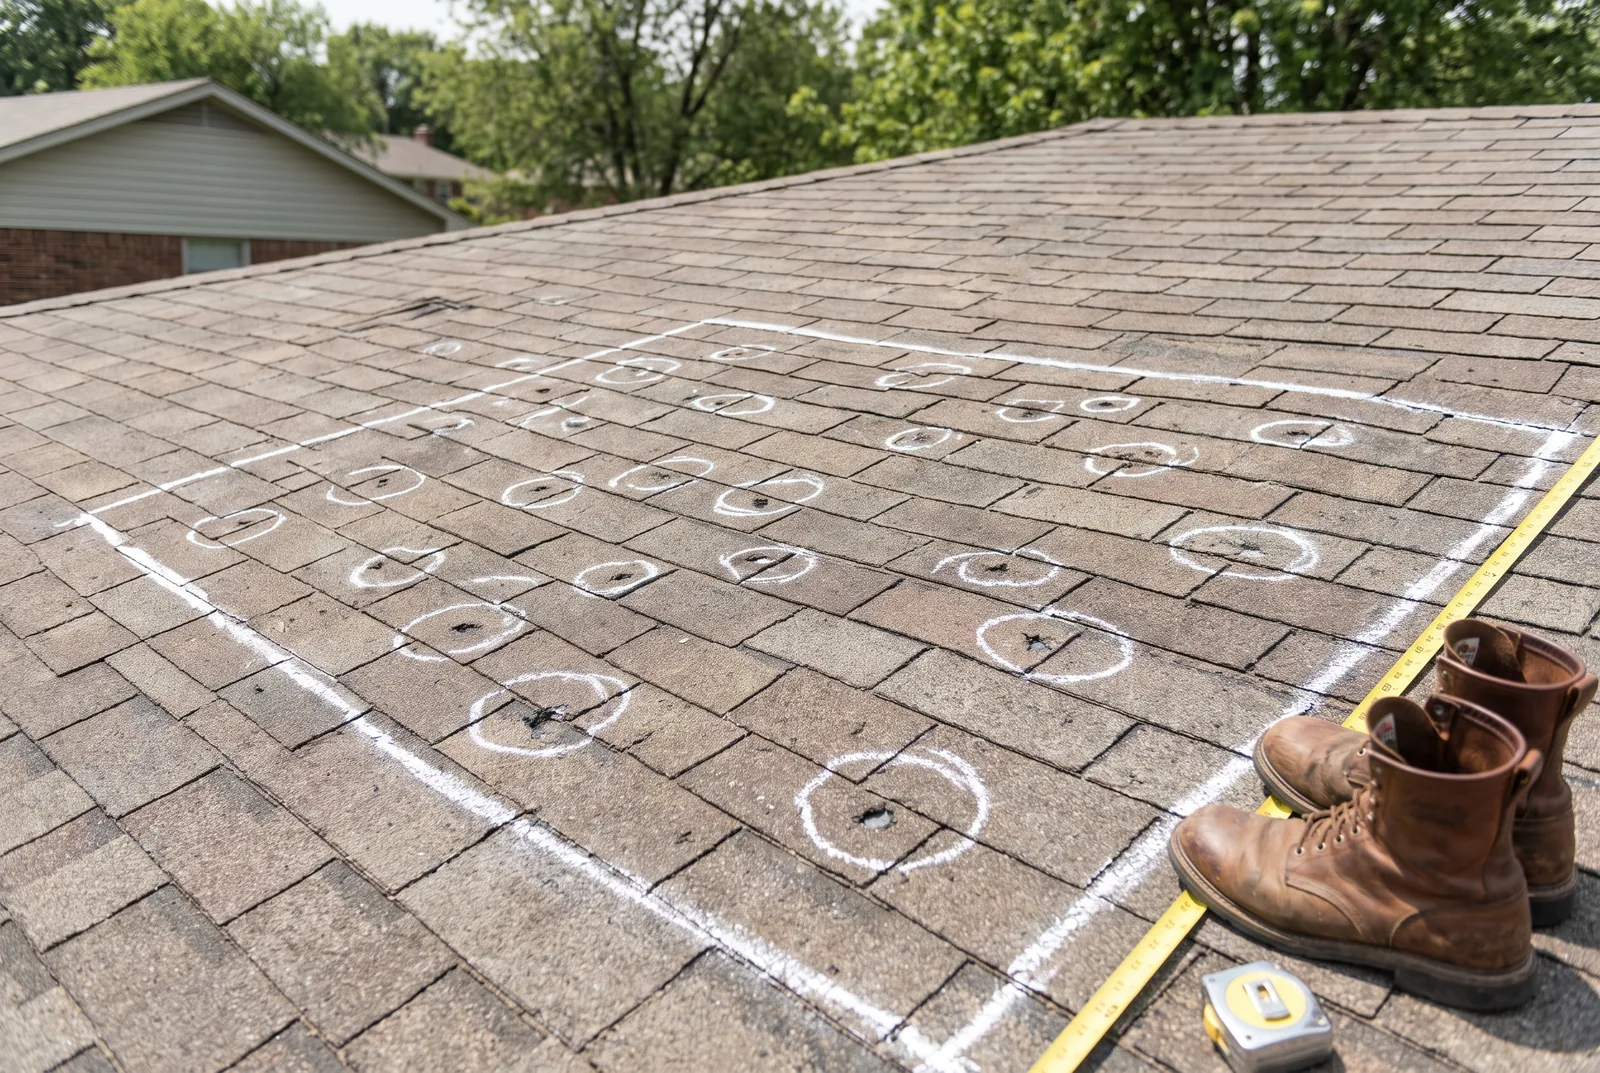
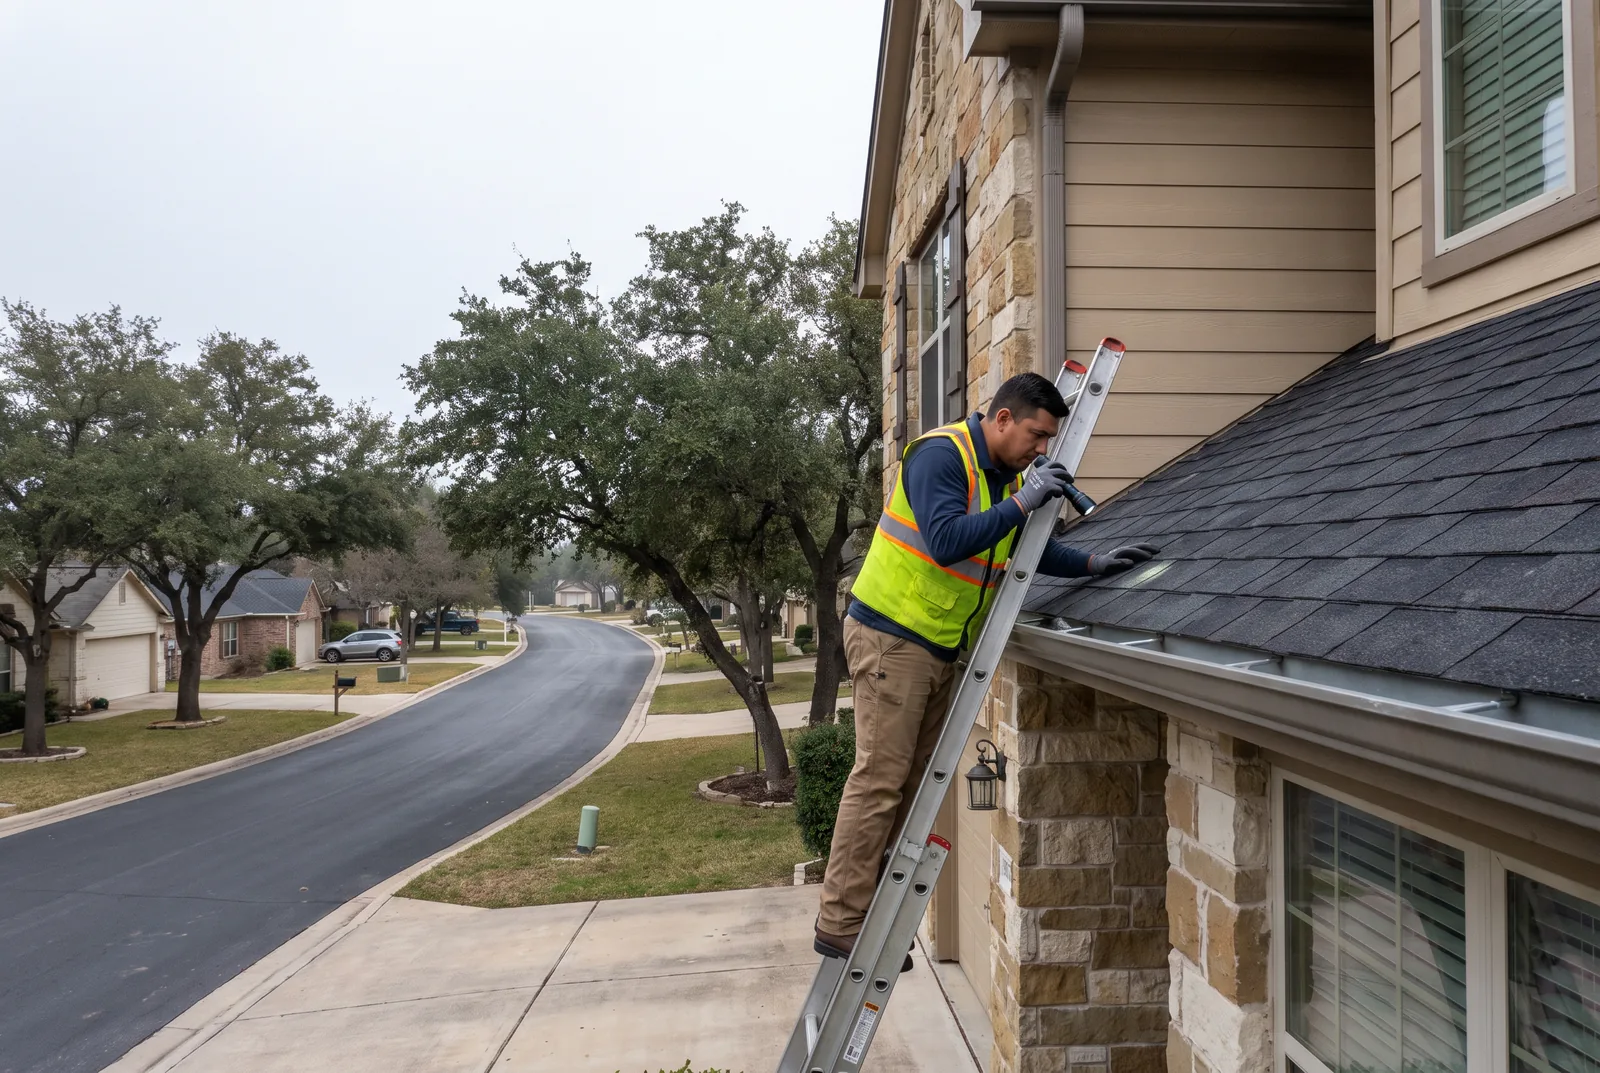
That's the job we do before a single shingle moves. We inspect the whole property — roof, gutters, vents, siding, screens, the AC — chalk test squares, photograph every hit with a date, pull the radar-confirmed hail and wind data for your address on the storm date, and write an itemized estimate in the same line-item format the adjuster's software uses. When the adjuster comes, we're on the roof with them. If they approve, we build to that scope; if the deck is soft or the code requires ice barrier the estimate missed, we document the supplement with photos. And we never, ever touch the deductible.
What's included
Pre-claim inspection
The whole hail story documented before you call the carrier, so you file knowing what you have.
Storm report
Radar hail size and wind gusts at your address on the date of loss, attached to the estimate.
Line-item estimate
Written in the format adjusters work from — squares, waste, tear-off, ice barrier, flashing, vents, code items.
Adjuster meeting
We meet your adjuster on the roof and walk the test squares together.
Supplements
Soft decking, missed slopes, code-required items — documented with photos and submitted properly.
Deductible: yours
Waiving, rebating or disguising a deductible is insurance fraud in Arkansas. We don't, and you shouldn't hire anyone who offers.
Roof insurance claims cost in Fayetteville, AR
| Job | Typical price | Notes |
|---|---|---|
| Pre-claim inspection, photos and storm report | Free | Whether or not you file |
| Adjuster walk-through | Free | Included with any claim we work |
| Replacement built to approved scope, architectural | $11,000 – $19,000 | Typical home; carrier pays less your deductible |
| Class 4 upgrade over the approved scope | +$2,000 – $4,500 | You pay the difference; discount often follows |
| Emergency tarp (covered mitigation) | $350 – $900 | Invoiced separately for the claim |
| Repair below deductible (no claim) | $400 – $1,800 | When filing doesn't make sense |
These are 2026 Northwest Arkansas ranges so you can budget. Your written price is itemized — tear-off, decking, underlayment, ice barrier, flashing, vents, disposal, permit — and good for 30 days.
Recent work
Questions we get about roof insurance claims
Should I call my insurance company or a roofer first?
A roofer — but only for the inspection. Filing a claim that gets denied still goes on your record, and if the damage is below your deductible or the roof is old enough to be paid at actual cash value, you may be better off not filing. Get the free inspection, see the photos, then decide.
What is my deductible on a hail claim?
Check your declarations page. Many Arkansas policies now carry a separate wind/hail deductible of 1 to 2 percent of the dwelling coverage — on a $350,000 house that's $3,500 to $7,000, not the $1,000 all-perils deductible you remember.
What's the difference between replacement cost and actual cash value?
Replacement cost pays what it costs to replace the roof today. Actual cash value pays that minus depreciation for the roof's age — on a 15-year-old shingle roof that can be half. Many Arkansas policies now switch from one to the other at about seven years; the insurance guide explains how to read yours.
Can you bill my insurance company directly or waive my deductible?
No, and be wary of anyone who offers either. You pay your deductible; the carrier pays you (or you and your mortgage company); you pay us. A roofer who "eats" the deductible is inflating the estimate to cover it, which is fraud for both of you.
The adjuster only approved one slope. What now?
That happens when hail hit from one direction. If our test squares show damage on the others, we submit the photos and a supplement request. If not, we replace the approved slope and colour-match as closely as the market allows.